Latest news
Ryan Peters, assistant professor at Tulane University's business school, believes that the U.S. GENIUS Act is a milestone in stablecoin regulation, but far from the end. The bill addresses the definition of stablecoins and regulatory attribution, mandates cash or short-term Treasury reserves, and ends the jurisdictional dispute between the Federal Reserve and the SEC. However, the bill does not require daily reserve transparency, nor does it address bank deposit outflows. The author calls on Congress to quickly introduce follow-up measures, including daily disclosure of reserve details, establishing outcome-based innovation channels, and setting up liquidity adjustment mechanisms.
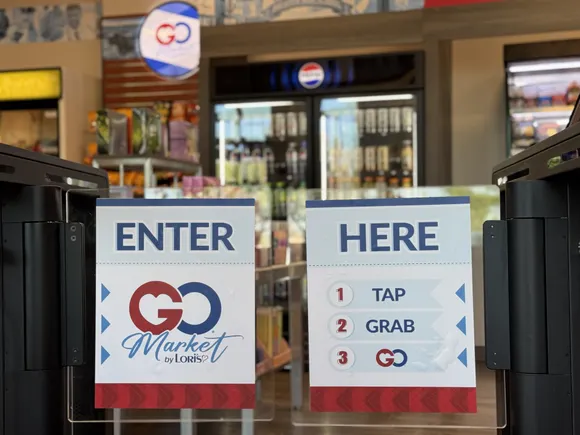
Checkout-free payment technology, after Grabango's collapse and Amazon's reduced investment, is still seen by industry experts as having great potential. Advances in AI, declining costs, and demand in specific scenarios such as sports venues may drive the technology's revival. This article synthesizes multiple perspectives to analyze its current state, challenges, and future.
Over the past six years, EWA has helped American workers manage daily finances and cope with emergency expenses. The 2020 advisory opinion clarified its non-credit nature, but the 2024 proposed rule and 2025 rescission created confusion. The author urges the CFPB to issue an expanded advisory opinion to confirm once and for all that EWA is not credit.
Earlier this year, the White House issued a directive requiring federal agencies to stop using paper checks as the default method for payments and collections by the end of September. This move is seen by industry insiders as a correction to a long-standing inefficient payment method. Chase Gilbert, CEO of Built Technologies, notes that paper checks are 16 times more likely to be lost or stolen compared to digital payments, and cost taxpayers hundreds of millions of dollars annually. Despite the clear evidence, 75% of businesses still rely on paper checks for B2B payments. Gilbert calls on the private sector to elevate payment digitization as a strategic priority to enhance security, transparency, and operational efficiency.
The ISO 20022 standard aims to unify the data exchange format among global financial institutions, and the implementation deadline for the Fedwire payment system has been extended to July 2025. While large banks have made significant progress, small and mid-sized banks and credit unions generally lag behind. Industry research shows that only 5% of financial leaders are confident in their current real-time payment processing capabilities. Experts suggest that institutions should leverage this compliance opportunity to drive system modernization, thereby enhancing operational efficiency, strengthening anti-fraud capabilities, and gaining a competitive advantage.
As Gen Z enters the workforce, they are reshaping B2B payments as digital natives: they demand instant settlement, transparent fees, flexible credit, and value alignment. Billtrust CEO Sunil Rajasekar believes that payments are no longer mere transactions but a litmus test of corporate values. Companies that cling to 30-day payment terms and cumbersome approvals will lose the trust of this generation of decision-makers.
The dollar has served as the world's reserve currency for over a century and is now undergoing digital transformation through stablecoins. With a value exceeding $200 billion, stablecoins offer a store of value for residents of high-inflation countries, reduce cross-border transfer costs, and promote financial inclusion. Although Bitcoin's volatility limits its payment functionality, dollar-pegged stablecoins (such as USDT and USDC) are rapidly gaining traction in regions like Latin America and sub-Saharan Africa, serving as a powerful complement to traditional fiat systems.
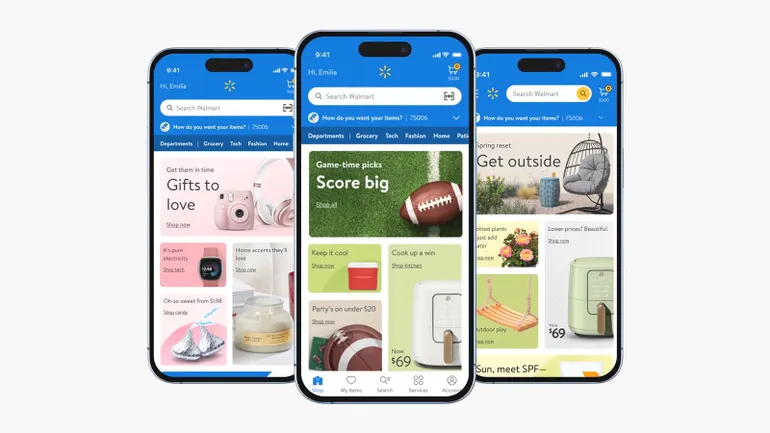
The payment industry is repeating the streaming playbook: an explosion of options that leaves consumers more confused. From digital wallets to BNPL, from direct bank connections to cryptocurrencies, fragmentation is intensifying. But history shows consolidation is inevitable—the winners will be those companies that make payments invisible.
With Trump back in office, payment fintech companies are expected to gain more regulatory space, including special-purpose national bank licenses and a federal framework for stablecoins. However, traditional financial institutions such as banks may come under pressure as a result. This article summarizes the views of industry lawyers, former officials, and recent policy developments.
Over a year after FedNow's launch, more than a thousand financial institutions have joined, but most have only enabled the receiving function. The author points out that only receiving without sending will put institutions at a competitive disadvantage and reputational risk, and recommends full integration as soon as possible.